
Estimated reading time: 12 minutes
Key Takeaways
- Average cold investor email open rates sit between 40 and 60%, with anything under 30% signalling deliverability or targeting problems.
- The average investor cold email reply rate for well-targeted campaigns is around 5 to 10% — generic blasts often stall at 1 to 3%.
- Not all replies are equal: always separate your total reply rate from your positive reply rate.
- Warm introductions live in a completely different benchmark universe, often converting at 70 to 80% reply rates.
- Benchmarks are a diagnostic tool, not a verdict — use them to identify where your funnel is breaking down.
Table of contents
- Quick Investor Email Benchmark Summary
- Investor Email Open Rate Benchmarks Explained
- Average Investor Cold Email Reply Rate: What to Realistically Expect
- What Is a Good Response Rate for Investor Outreach?
- Open Rate vs Reply Rate vs Click Rate: What Each Metric Actually Tells You
- Benchmark Differences by Outreach Type
- Factors That Influence Investor Outreach Benchmarks
- How to Diagnose Your Campaign Performance
- How to Improve Investor Email Open Rates
- How to Improve Investor Reply and Response Rates
- Example Investor Outreach Benchmark Scenarios
- Common Mistakes When Interpreting Investor Email Benchmarks
- Recommended Tracking Setup for Investor Outreach
- Final Benchmark Takeaways
- Putting It All Together
- Frequently Asked Questions
If you are running an investor outreach campaign, one of the first questions you will ask is: “Are my numbers good?”
That question is exactly why investor email open rate benchmarks matter. Without a reference point, it is impossible to tell whether your campaign is performing well, falling short, or simply in line with what most founders experience.
This post gives you realistic, data-backed benchmarks for every stage of investor email performance. Open rates. Click rates. Reply rates. Positive response rates. Meeting-booking rates. And a clear framework for diagnosing what to fix when the numbers are not where you want them.
Before diving in, it is worth being honest about one thing: investor email performance depends on many variables. These include:
- The quality of your investor targeting
- Whether the outreach is warm or cold
- Your company stage and traction
- How personalised and relevant the email is
- Your founder credibility and background
- The strength of your fundraising narrative
- Current market conditions and investor appetite
Benchmarks are directional guides, not fixed guarantees. Use them to diagnose, not to judge.
Quick Investor Email Benchmark Summary
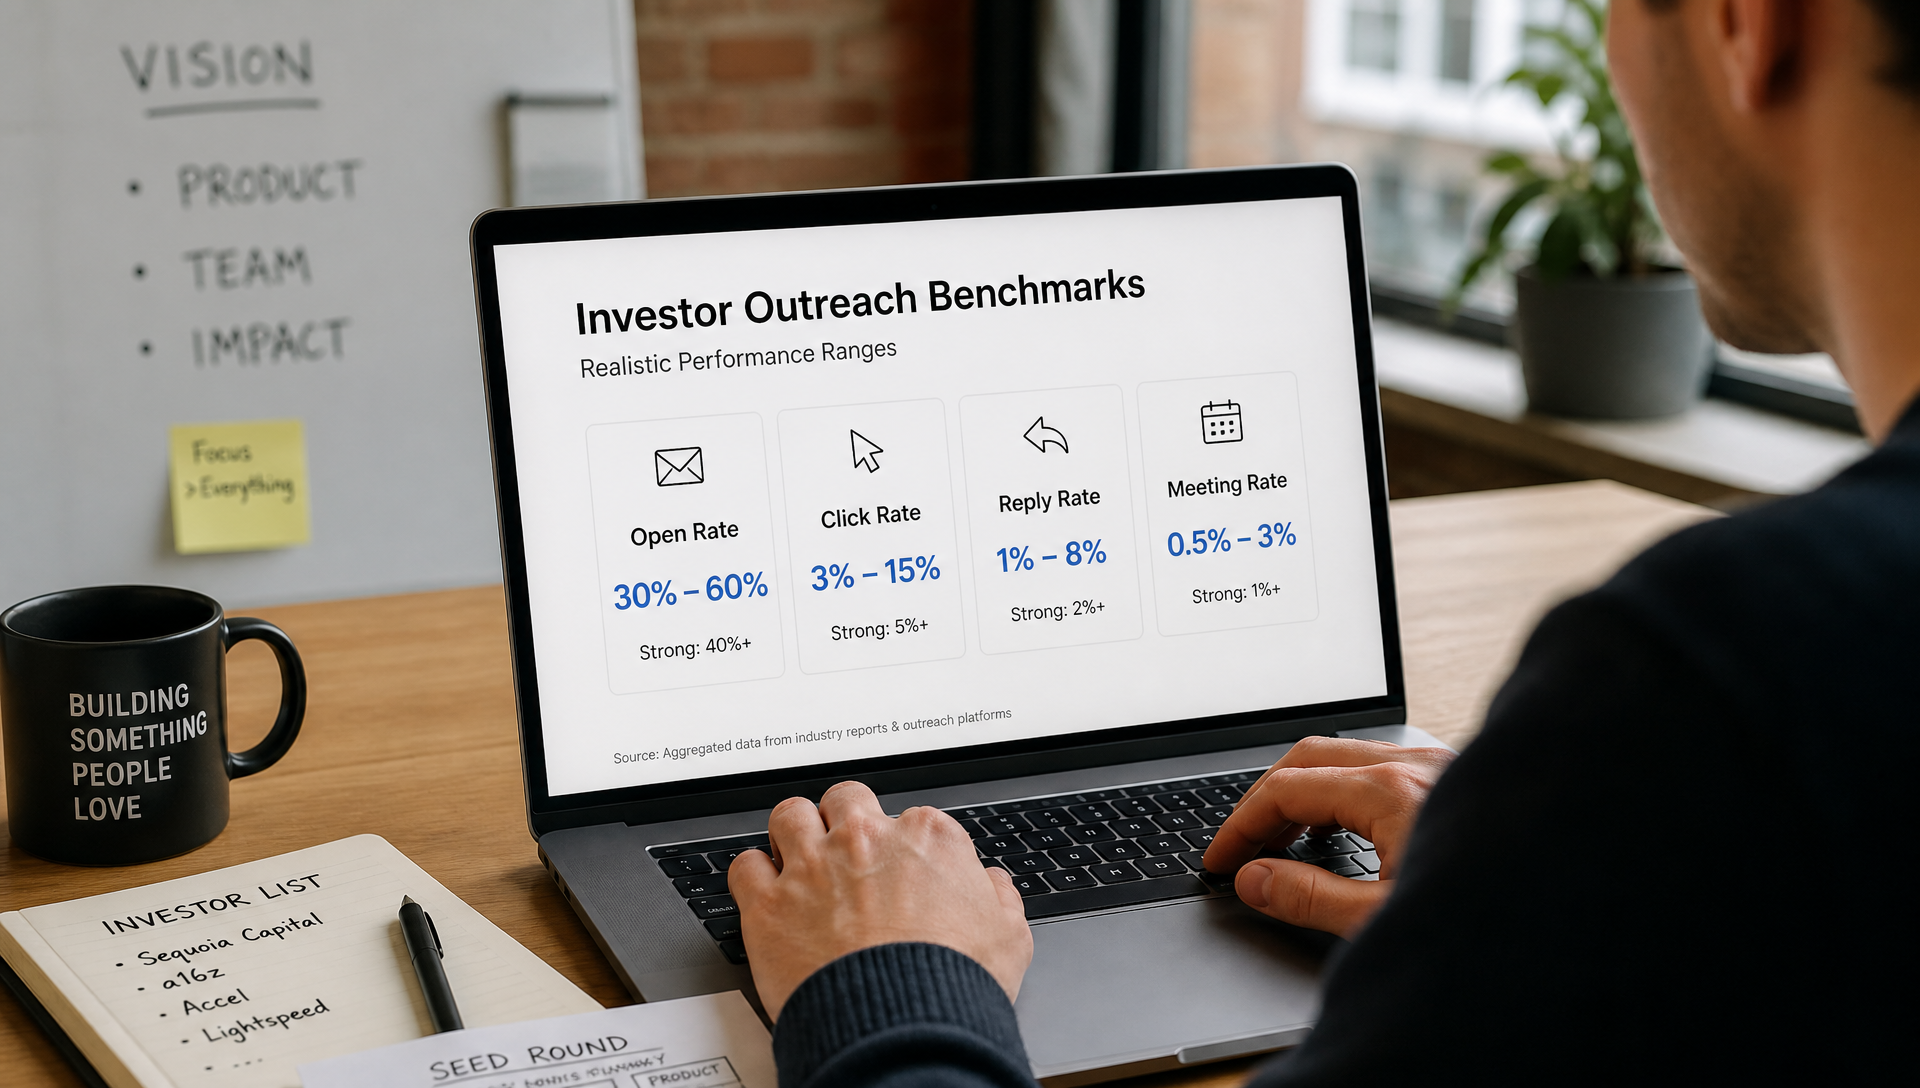
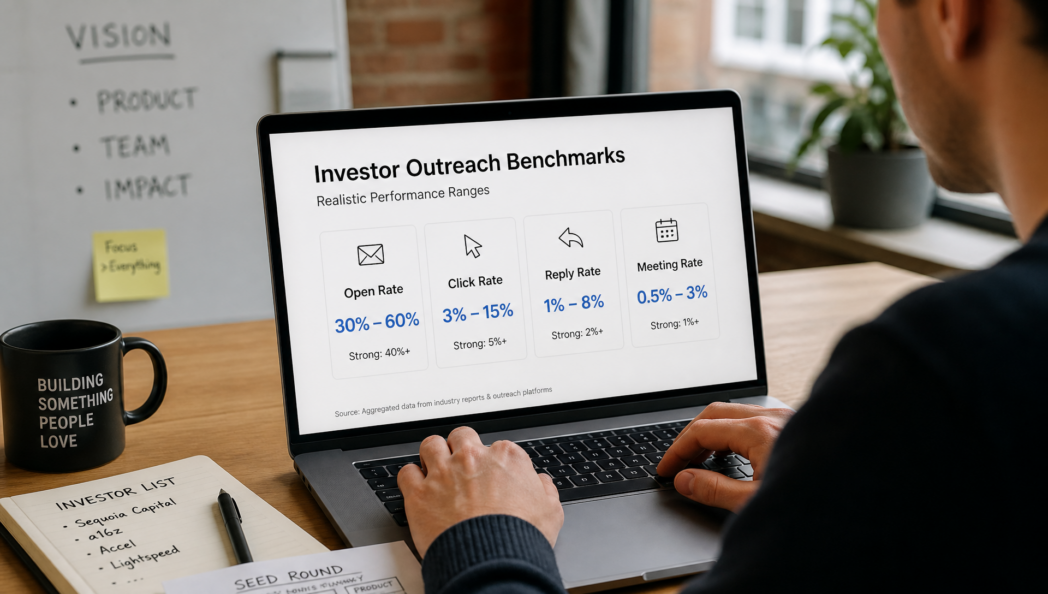
Before going deep, here is the full benchmark table at a glance. These ranges are based on recent 2025 to 2026 investor outreach data and fundraising-specific reports.
| Metric | Weak | Average | Good | Excellent |
|---|---|---|---|---|
| Open rate | Under 30% | 40 – 60% | 60 – 75% | 75%+ |
| Click rate | Under 2% | 2 – 5% | 5 – 10% | 10%+ |
| Total reply rate | Under 3% | 5 – 10% | 10 – 20% | 20%+ |
| Positive reply rate | Under 1% | 2 – 5% | 5 – 10% | 10%+ |
| Meeting-booked rate | Under 1% | 1 – 3% | 3 – 7% | 7%+ |
These benchmarks vary by sector, company stage, investor type (VC vs angel vs family office), geography, and investor list quality. Use them as a starting point, not an exact target.
Investor Email Open Rate Benchmarks Explained
Open rate measures how many of the investors you contacted actually opened your email. It is the first data point most founders look at, and it tells you whether your email got through the noise.
Recent fundraising-specific data shows that cold investor email open rates typically fall in the 35 to 65% range, depending on personalisation and list quality. Here is how to interpret your own numbers against these investor email open rate benchmarks:
- Under 30%: Weak. Likely points to deliverability problems, poor subject lines, a weak or mismatched investor list, or emails landing in spam.
- 40 to 60%: Average. Consistent with lightly personalised or generic founder outreach. A reasonable starting point, but there is room to improve.
- 60 to 75%: Strong. Typical of targeted, personalised cold campaigns sent to well-matched investors.
- 75%+: Very strong. More common with highly targeted lists or warm and warm-adjacent outreach where the investor already has some familiarity with the founder or referrer.
What a high open rate suggests:
- Your subject line is working
- The investor recognises your name or referrer
- Your email landed cleanly in the inbox
- Your targeting is on point
What a low open rate suggests:
- Weak or vague subject line
- Generic outreach with no personalisation
- Poor sender reputation or deliverability issues
- Emails going to the wrong investor segment
One important caveat about open tracking:
Recent cold email benchmark reports argue that open rate is becoming a “structurally broken” metric. Tools like Apple Mail Privacy Protection automatically trigger the tracking pixel even when no human has opened the email. This inflates open rate figures and makes them less reliable as a measure of genuine engagement.
Treat open rate as a directional signal. Focus more heavily on clicks, replies, and meetings as your primary performance indicators.
Average Investor Cold Email Reply Rate: What to Realistically Expect
Reply rate is more important than open rate. An investor who opens your email but does not reply has not moved your fundraise forward. An investor who replies has.
The average investor cold email reply rate is one of the hardest metrics for founders to find honest data on. Many sources either inflate it with optimistic anecdotes or deflate it with worst-case scenarios.
Based on 2025 to 2026 investor outreach data, here is what the numbers actually look like:
- Under 3%: Weak. This is where generic mass blasts typically land. Low fit, weak copy, and no personalisation.
- 5 to 10%: Average. Consistent with reasonably targeted, personalised cold outreach from founders.
- 10 to 20%: Good. Strong targeting and messaging. Often seen when investors are explicitly open to cold pitches and there is clear thesis alignment.
- 20%+: Excellent. Top-tier campaigns with very tight investor-founder fit, strong traction, and highly personalised messaging.
For context: overall B2B cold email reply rates across all industries fell to around 3.43% by 2026. Generic cold pitches to VCs without strong targeting often convert at only 1 to 2%. Some VC-focused guides note that as many as 95% of cold pitches receive no reply at all for founders with no connection.
This means that even a 10% reply rate on a well-targeted campaign is genuinely strong performance.
Not all replies are equal.
This is a critical distinction most founders overlook. Your total reply rate includes every response you receive, including:
- “Not interested”
- “Too early for us”
- “Not our thesis”
- “Passed, but good luck”
Your positive reply rate only counts replies that indicate real engagement:
- Deck requests
- Intro calls booked
- Partner referrals
- “Yes, let’s talk” responses
For cold investor outreach, realistic positive reply rate benchmarks look like this:
- Average cold campaign: 2 to 5% positive replies
- Strong campaign with matched targeting: 5 to 10%+ positive replies
- Highly personalised, traction-heavy outreach: up to 8 to 15% positive replies
A campaign can look decent on total reply rate while still having very few genuinely interested investors. Tracking the two separately is essential.
What Is a Good Response Rate for Investor Outreach?
A good response rate for investor outreach is not a single number. It depends entirely on what type of outreach you are running.
Response rate is simply: the number of replies divided by the number of emails sent.
But the definition of “good” shifts significantly based on your campaign type:
Broad, low-personalisation cold campaign:
- Normal range: 3 to 7% total replies
- Most of these will be polite rejections
- This is a weak result, but it is common when outreach is not well targeted
Targeted cold investor list (matched on stage, sector, geography):
- Good range: 8 to 15% total replies
- A meaningful share of these will be genuine interest
- This aligns with multiple reports showing 5 to 15% response rates when investors are properly matched
Highly personalised investor outreach:
- Strong range: 15 to 25%+ total replies
- Consistent with top-decile benchmarks where personalisation and traction are both present
Warm introductions:
- Often far higher – some VC-specific data points show 70 to 80% reply rates for warm intros
- Meeting conversion rates are also significantly higher than cold outreach
Judging “good” by quality, not just quantity:
A good response rate for investor outreach should be measured by meaningful outcomes, not just raw numbers. What actually matters is:
- Replies from relevant investors
- Deck requests
- Intro calls scheduled
- Partner-level meetings
- Serious diligence conversations or term sheet discussions
A single high-quality reply from the right lead investor can matter more than thirty polite “not for us” responses.
Open Rate vs Reply Rate vs Click Rate: What Each Metric Actually Tells You
Each metric in your investor email funnel answers a different question.
Open rate: Did the investor open the email? This tells you about your subject line, sender credibility, deliverability, and investor list relevance. It does not tell you whether they were interested in what you wrote.
Click rate: Did the investor click on something in the email – a pitch deck link, a data room, a calendar booking link, or your website? A click indicates active interest and intent. This is a much stronger signal than an open. Average click rates for investor outreach sit in the 2 to 5% range, with strong campaigns reaching 5 to 10%+.
Reply rate: Did the investor write back? This is the metric that most directly moves your fundraise forward. Whether positive or negative, a reply means the email was read and considered.
Positive reply rate: Of the investors who replied, how many showed genuine interest? This filters out rejections and polite passes. It is the true measure of campaign effectiveness.
Meeting-booked rate: How many investors converted into an actual call or meeting? This is the bottom of the funnel and the closest indicator to real fundraising progress. Average meeting rates from cold outreach sit around 1 to 3%, with strong campaigns reaching 3 to 7%+.
Key patterns to watch for:
- High open rate with low replies: Your subject line and deliverability are fine. The email body, pitch relevance, or call to action needs work. Investors are looking but not engaging.
- Low open rate with decent replies: Your offer may be strong, but visibility and deliverability are dragging performance down. Fix the subject line and sender setup first.
- High replies but very few meetings: There is interest but not conviction. The fundraising ask may be unclear, or traction and positioning may not be strong enough to convert curiosity into commitment.
Benchmark Differences by Outreach Type
Not all investor outreach is the same. The channel and relationship context you use has a significant effect on performance.
Warm introductions: The highest-performing outreach type. VC partners often respond to warm intros at 70 to 80% rates, and a high share of those replies convert to meetings. Warm intros benefit from trust transfer – the referrer has already screened you in the investor’s eyes. This reduces friction dramatically.
Cold email (targeted): A well-crafted, targeted cold email campaign can reach 8 to 15% total reply rates and 5 to 10% positive replies. Cold outreach can work, but it requires clear thesis alignment, a concise pitch, personalised reasoning, and strong traction signals.
Cold email (generic): Response rates frequently sit at 1 to 5% for untargeted campaigns. Only a small fraction – around 1 to 2% – convert into actual meetings.
LinkedIn-assisted email: When a founder has engaged with an investor on LinkedIn before emailing – commenting on a post, sharing a relevant article, or responding to their content – the email feels less cold. This “warm-adjacent” approach can lift open and reply rates closer to the targeted cold range or above it.
Founder update or existing relationship email: When reaching out to investors who already know your company – previous meeting attendees, newsletter subscribers, or angels you have worked with before – reply rates and meeting conversion rates increase significantly. The investor already has context.
Investor newsletter or founder update: This type of outreach performs differently. It is not a cold pitch, but a relationship maintenance tool. Reply rates are lower in volume but often higher in quality when an investor responds.
Founders should never directly compare cold outreach metrics to warm intro performance. They exist in different benchmark universes entirely.
Factors That Influence Investor Outreach Benchmarks
Benchmarks are only useful when you compare them against similar outreach conditions. The following variables have a direct impact on every metric in your investor email funnel:
Investor targeting quality: Tightly qualified lists consistently outperform broad, generic databases across every metric. Strong targeting improves performance more reliably than sending higher volume.
Fund thesis alignment: Investors who actively back your sector, stage, and geography are far more likely to engage than those who receive mismatched pitches.
Company stage and traction: Later-stage companies with hard metrics – revenue, growth rate, retention – see higher positive reply rates and meeting conversions. Traction in the subject line or opening sentence lifts replies meaningfully.
Market category and investor appetite: Hot categories (such as AI, climate, and fintech at different points in the cycle) attract higher engagement from investors actively looking to deploy in those spaces.
Founder background: Repeat founders and strong domain experts tend to get better engagement. Credibility signals matter before the investor has even read the email.
Email personalisation: Tailored emails that reference an investor’s thesis, portfolio, or recent content see multiples of generic reply rates. Personalised campaigns regularly show reply rates of 8 to 20%, compared to 3 to 8% for generic outreach.
Email subject line: Clear, specific, traction-oriented subject lines outperform vague or hype-heavy ones. Brevity and relevance win.
Timing in the fundraising cycle: Funds actively deploying capital, or explicitly open to inbound, respond more. Reaching an investor mid-deployment is very different from contacting them when a fund is fully allocated.
Fund size and cheque size: Misaligned ticket sizes reduce positive responses. A pre-seed founder targeting growth-stage VCs will see poor results regardless of email quality.
Follow-up sequence: Teams that run thoughtful follow-up sequences of 2 to 4 emails get meaningfully higher cumulative reply rates than founders who send one email and wait.
How to Diagnose Your Campaign Performance
If your numbers are not where you want them, the benchmark table is your diagnostic starting point. Here is how to read the patterns:
Low open rate (under 30%): The problem is before the email body. Look at: subject line quality, sender email address and domain reputation, email deliverability setup (SPF, DKIM), and whether your investor list is relevant and clean.
High open rate but low reply rate (e.g., 60% opens, 3% replies): Visibility is not the problem. Investors are opening but not responding. Look at: email body quality, how clearly you state your pitch, whether the investor is genuinely a fit for your stage and sector, and whether your call to action is clear and easy to act on.
High reply rate but few meetings (e.g., 15% replies, 2% meetings): There is interest but not enough conviction to take a meeting. The replies may be mostly polite passes. Look at: whether your fundraising ask is clear, whether your traction and positioning are strong enough to justify a meeting, and whether the investor fit is genuinely high quality or just surface-level aligned.
Good meetings but no follow-on interest or offers: The underlying narrative needs work. Look at: your pitch deck, your key metrics, your valuation expectations, and the clarity of your fundraising story.
Many clicks but no replies: Investors are curious enough to click on your deck or link, but not compelled enough to respond. The deck or offer may not be strong enough to convert interest into action.
Treat these benchmarks as a diagnostic tool. They point to where the bottleneck is, not to whether your startup is fundable.
How to Improve Investor Email Open Rates
The goal is to move from the weak or average bands in the investor email open rate benchmarks into the strong or very strong ranges. Here are the most effective tactics:
Use clear, specific subject lines: Subject lines that include your company name, category, and a traction point consistently outperform vague or generic ones. Examples that work:
- “Seed round for [Company] – [short traction point]”
- “[Mutual connection] suggested I reach out”
- “[Company]: [category] startup growing [metric]”
Lead with credibility early: Mention your company name, category, a key metric, or a mutual connection in the subject line or preview text. Investors scan their inbox quickly, and credibility signals decide whether they open.
Avoid spammy language: Words and phrases like “once-in-a-lifetime opportunity” or “exclusive deal” harm both deliverability and how seriously investors take your message. Keep the language professional and specific.
Send from a real founder email address: Investors expect emails authored by the founder directly. Sending from a generic marketing automation address or a no-reply domain reduces both open rates and reply rates. Use your real name and company domain.
Keep your investor list relevant: Match your list on stage, sector, geography, cheque size, and fund thesis. Reaching the right 100 investors is more valuable than reaching the wrong 1,000.
Fix deliverability before large sends: Set up SPF and DKIM authentication on your sending domain, warm the domain before bulk sends, and clean your list to remove invalid or stale addresses. Poor deliverability can suppress open rates even when everything else is working.
For more tactical examples, see these cold email templates for reaching investors.
How to Improve Investor Reply and Response Rates
Improving the average investor cold email reply rate and achieving a good response rate for investor outreach comes down to relevance, clarity, and follow-through. Here is what actually moves the needle:
Personalise the opening line: Reference the investor’s thesis, a portfolio company, or a piece of content they published. Something like: “We are building in a similar space to [portfolio company], but focused on [specific segment].” Personalised campaigns consistently show reply rates of 8 to 20%, compared to 3 to 8% for generic outreach.
Explain why you are contacting this specific investor: Make it obvious that you have done your research. Mention their stage focus, sector, geography, or a specific reason why your company fits their mandate.
Lead with traction immediately: State your category and a key metric in the first one or two sentences. Busy investors will not read three paragraphs to find out what you do.
Keep the email short and scannable: Long emails get skimmed or ignored. Aim for five to eight sentences maximum. Every sentence should earn its place.
Make the ask clear and simple: One call to action works best. For example: “Would you be open to a 20-minute intro call next week?” Give the investor a single, easy decision to make.
Do not attach files in the first email: Large attachments can trigger spam filters and feel presumptuous. Offer to send the deck on request, or include a short link if it is essential.
Include a sharp two-line teaser: One or two key numbers plus a clear thesis sentence. Give the investor just enough to understand what you do, why now, and why it fits them – without overwhelming them with detail.
Follow up 2 to 4 times: Investor outreach data consistently shows higher cumulative reply rates with thoughtful follow-up sequences. Polite persistence is not pushy – it is professional. Many replies come after the second or third email.
When investors can instantly understand what the company does, why this is the right time, why the founder is credible, why it fits their mandate, and what the next step is – reply rates go up.
Example Investor Outreach Benchmark Scenarios
These scenarios help translate the benchmarks into practical comparisons.
Scenario 1: Broad cold campaign (underperforming)
- 500 broad cold emails sent to a mixed investor list
- 35% open rate, 3% total reply rate, under 1% positive replies
- What this teaches: Open rate is below average, and reply rate sits at the bottom of the normal range. This is a targeting and personalisation problem. The volume of sends does not compensate for the lack of fit.
Scenario 2: Well-targeted cold campaign (healthy)
- 150 targeted cold emails to carefully matched VCs and angels
- 65% open rate, 12% total reply rate, 6% positive replies, 3 to 4% meeting-booked rate
- What this teaches: Strong open and reply metrics that align with the “good” range in the benchmark table. Smaller volume, better results. Quality targeting outperforms raw send volume.
Scenario 3: Warm intro campaign (strong, not comparable to cold)
- 50 warm introductions via trusted referrers in the founder’s network
- 85% open rate, 40% reply rate, 25% meeting-booked rate
- What this teaches: Performance is dramatically higher across every metric. This is consistent with warm intro benchmarks and illustrates how much trust transfer matters. These numbers should not be compared to cold outreach expectations.
Scenario 4: Founder update to existing investor relationships
- 80 emails sent to investors who attended a demo day, met at a conference, or subscribed to a founder update
- 70 to 75% open rate, 20 to 30% reply rate, 10%+ meetings booked
- What this teaches: Prior familiarity and context lift every metric. Maintaining investor relationships before you need them makes the fundraising ask significantly easier.
Common Mistakes When Interpreting Investor Email Benchmarks
Knowing the numbers is only useful if you interpret them correctly. These are the most common mistakes founders make:
Obsessing over open rates instead of replies: Open rates are noisy and increasingly unreliable. A high open rate with no replies means nothing has moved forward. Focus on reply rate and positive reply rate as your primary performance signals.
Comparing cold outreach to warm intro benchmarks: These are completely different outreach types. Expecting cold email performance to match warm intro results will leave you constantly disappointed. They live in separate benchmark universes.
Treating all replies as equal: A polite “not for us at this stage” is not the same as a “can we schedule a call?” Separate your total reply rate from your positive reply rate. Always.
Sending too broadly: Sending 500 emails to a generic investor list will almost always produce worse results than sending 100 emails to a carefully matched list. Volume is not a substitute for targeting quality.
Not segmenting results: If you do not separate results by cold vs warm, investor stage focus, sector fit, geography, and cheque size, you cannot draw useful conclusions from your benchmarks. Mixed data produces mixed insights.
Over-automating personal outreach: Automation at scale reduces the personalisation that makes emails work. A high send volume with generic copy will pull your reply rate down even if your open rate looks decent.
Giving up after one email: A significant share of replies come from follow-up emails. Stopping at one send means missing investors who were interested but simply did not respond in the first pass.
Ignoring deliverability: If your domain reputation is poor or your emails are landing in spam, your open and reply rates will be artificially suppressed regardless of email quality.
Recommended Tracking Setup for Investor Outreach
To make benchmarks useful, you need to track the right data. A simple spreadsheet or CRM will do. For each investor, record:
- Investor name and firm
- Investor type (VC, angel, family office, corporate)
- Outreach source (cold, warm intro, LinkedIn, event)
- Email sent date
- Opened (yes/no, directional)
- Clicked (yes/no, what they clicked)
- Replied (yes/no)
- Reply sentiment (positive, neutral, rejection)
- Follow-up sent (date and sequence number)
- Meeting booked (yes/no)
- Outcome (meeting held, deck requested, passed, no response, in diligence)
Segment your results by:
- Cold vs warm outreach
- Investor stage focus (pre-seed, seed, Series A)
- Geography
- Sector and thesis fit
- Cheque size
Segmentation is what turns raw numbers into useful benchmarks. A 10% overall reply rate means very different things if 8% comes from warm intros and 2% comes from cold emails. Breaking it down tells you where to invest more effort.
Final Benchmark Takeaways
Here is what to carry forward from this post:
Investor email open rate benchmarks are useful as a starting point, but they do not tell the full story. Average cold campaigns land in the 40 to 60% open rate range, with under 30% suggesting real problems and 60 to 75%+ indicating strong targeting or a warmer relationship context.
The average investor cold email reply rate for reasonably targeted campaigns sits around 5 to 10%. Generic mass blasts are often stuck at 1 to 3%. If you are hitting 10 to 20% reply rates on a cold campaign, you are performing well.
A good response rate for investor outreach depends on how you are reaching investors. For targeted cold outreach, 10%+ total replies with 5 to 10%+ positive replies is strong. Warm introductions operate in a completely different performance range and should never be used as a cold outreach benchmark.
Reply quality and meeting conversions matter far more than raw open rates. A campaign with a 25% open rate and five genuine investor conversations is more valuable than one with a 70% open rate and zero meetings.
Before sending more emails, improve three things: targeting, messaging, and follow-up. Volume without those three will produce more of the same weak results.
Putting It All Together
Investor outreach is partly a numbers game, but it is not only a volume game.
Benchmarks exist to help you diagnose and improve, not to make you feel good or bad about your campaign. If your open rates are low, fix visibility. If your replies are low, fix relevance. If your meetings are low, fix investor fit and the strength of your pitch.
Use the benchmarks in this post to identify where your campaign is losing momentum. Adjust one variable at a time. Measure what changes. Repeat.
The founders who raise successfully are rarely the ones who sent the most emails. They are the ones who sent the right emails to the right investors with a clear, compelling reason for each one.
Frequently Asked Questions
What is a good open rate for investor cold emails?
A good open rate for cold investor emails typically sits between 60 and 75%. Under 30% is weak and points to deliverability or targeting problems, while 75%+ is considered very strong and often reflects warm-adjacent outreach.
What is the average investor cold email reply rate?
For reasonably targeted cold campaigns, the average reply rate sits around 5 to 10%. Generic, untargeted blasts often fall to 1 to 3%, while highly personalised campaigns can exceed 20%.
What is a good response rate for investor outreach?
It depends on the outreach type. Targeted cold campaigns often see 8 to 15% total replies, highly personalised campaigns can reach 15 to 25%+, and warm introductions frequently see 70 to 80% reply rates.
Why is my open rate high but my reply rate low?
This usually means your subject line and deliverability are working, but the email body, pitch relevance, or call to action is not compelling enough. Investors are looking but not engaging with the content.
Should I compare cold email results to warm intro results?
No. Warm introductions and cold outreach exist in completely different benchmark universes. Warm intros benefit from trust transfer and consistently outperform cold email across every metric, so comparing the two will give a misleading picture of performance.
What matters more: total reply rate or positive reply rate?
Positive reply rate matters more. Total reply rate includes polite rejections and passes, while positive reply rate isolates genuine interest such as deck requests, intro calls, and referrals. This is the true measure of campaign effectiveness.