
Estimated reading time: 12 minutes
Key Takeaways
- The short answer: send 2–4 thoughtful follow-ups after your initial investor email, with 3 meaningful touchpoints being the standard.
- Nearly 40% of positive responses come from follow-ups, not the first email.
- Reply rates decay fast after the fourth touch – diminishing returns kick in quickly.
- Targeting, email length, and personalisation matter far more than raw follow-up volume.
- Stop active follow-ups after 3–4 unanswered messages and shift to a long-term update cadence instead.
Table of contents
- Quick Answer – How Many Follow Up Emails to Send Investors
- Why Follow-Ups Matter in Investor Outreach
- Investor Follow Up Reply Rate Stats and What They Mean
- Best Number of Follow Ups for Investor Outreach
- Follow-Up Cadence – When to Send Each Email
- What Each Investor Follow-Up Should Say
- Effective Investor Follow-Up Angles That Drive Replies
- When to Stop Following Up With Investors
- Common Mistakes Founders Make With Investor Follow-Ups
- How to Improve Investor Follow-Up Reply Rates
- Warm Intro vs Cold Investor Follow-Up Strategy
- Suggested Investor Follow-Up Sequence You Can Copy
- How to Measure Your Own Investor Follow Up Reply Rate Stats
- Practical Recommendation by Fundraising Scenario
- Conclusion
- Frequently Asked Questions
If you’re wondering how many follow up emails to send investors, the short answer is usually 2–4 thoughtful follow-ups after the first email.
But that range matters a lot. Send too few and you leave real opportunities on the table. Send too many low-value messages and you risk damaging your credibility with the exact people you’re trying to impress.
Most investor replies do not come from the first email alone. Inboxes are noisy, timing is rarely perfect, and busy investors defer decisions constantly.
A structured follow-up sequence is not pushy – it is professional.
This post covers the data behind investor reply rates, the best number of follow-ups for investor outreach, a practical cadence you can copy, and clear rules for when to stop.
Quick Answer – How Many Follow Up Emails to Send Investors
Here is the recommended sequence based on fundraising outreach benchmarks:
- Day 0: Initial email
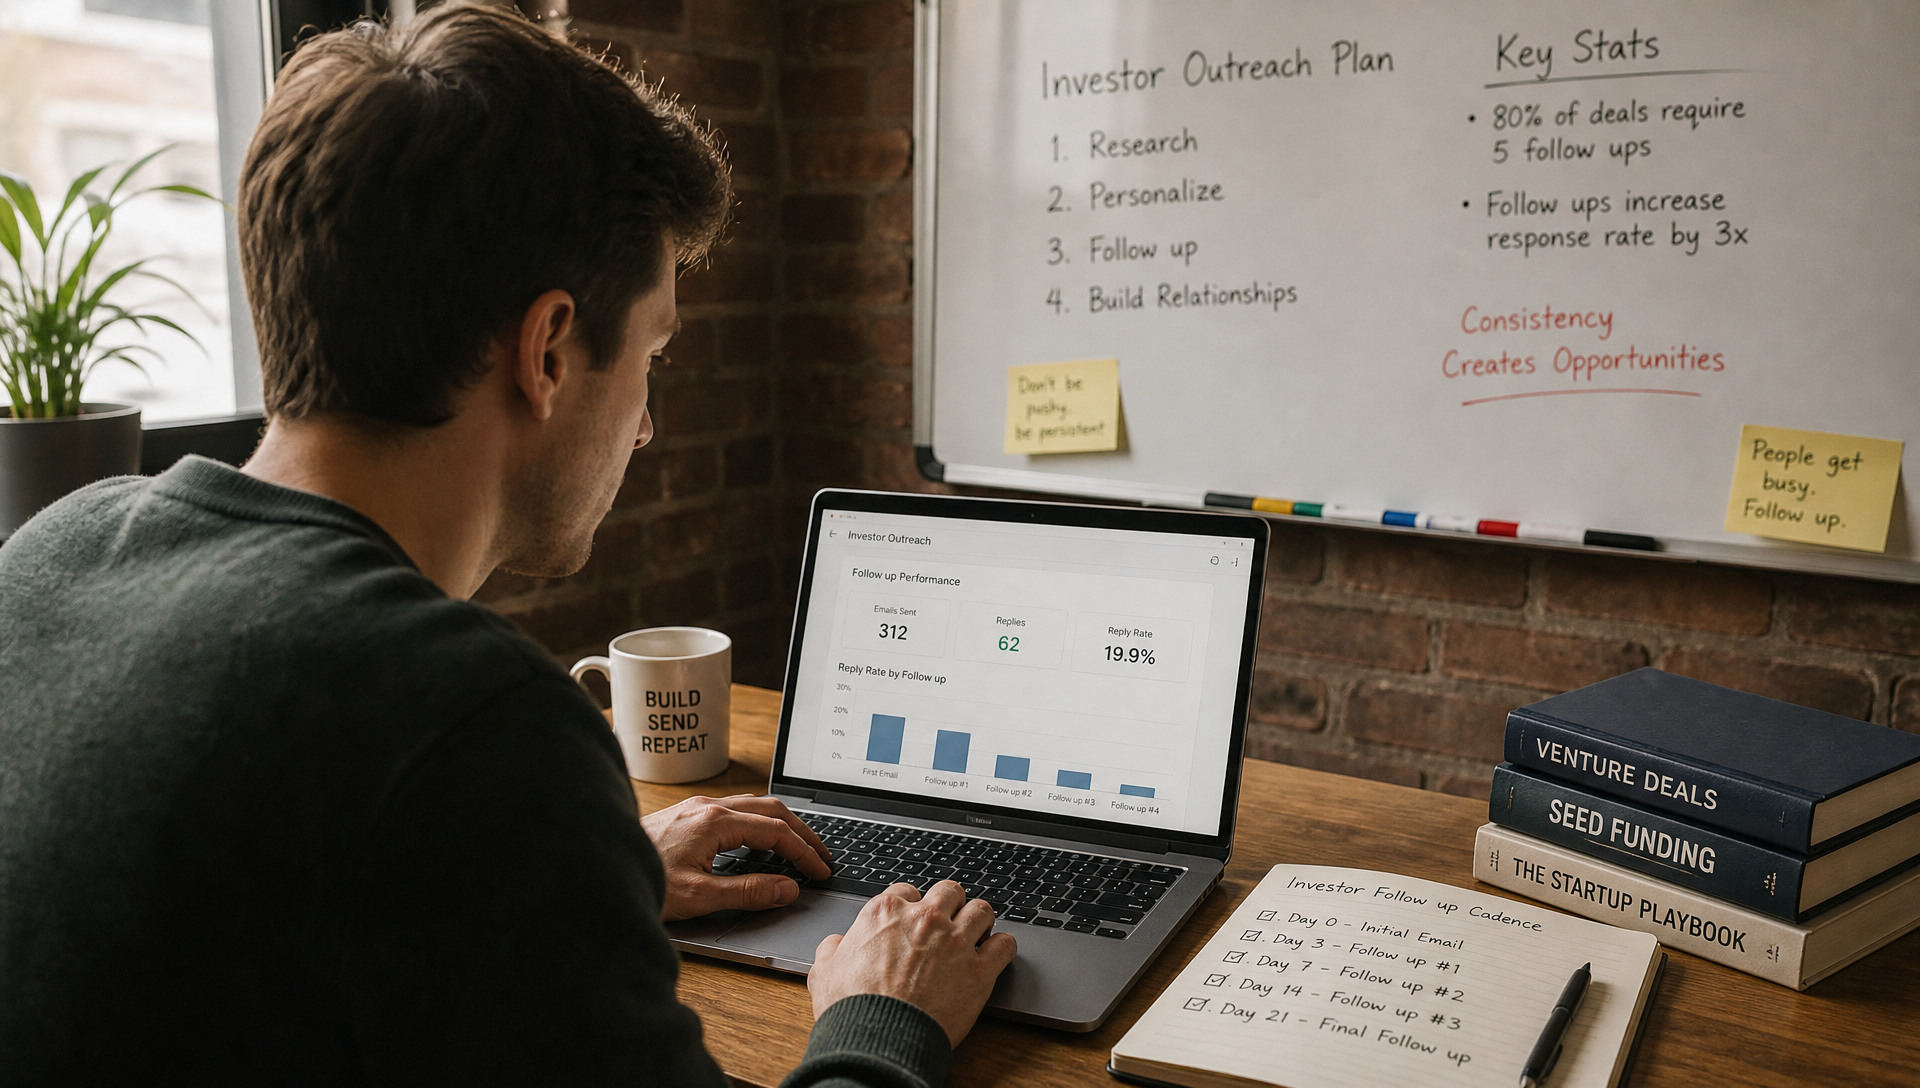
- Day 3–5: Follow-up 1
- Day 7–10: Follow-up 2
- Day 14–21: Follow-up 3
- Day 30+: Optional close-the-loop email
That gives you three meaningful follow-ups plus a final short message to close the loop.
The ideal number shifts depending on context:
- Cold outreach to a strong-fit investor: 3–4 follow-ups
- Warm introduction: 1–3 follow-ups before re-engaging your mutual contact
- Investor who has shown prior interest: Follow up until you have a clear answer, but only when you have something new to say
- Misfit investor: Stop sooner once you confirm the stage, sector, or geography is off
According to fundraising-specific outreach guides, most founders should stop after 3–4 unanswered follow-ups and shift the investor to lower-frequency update communications rather than continued chase emails, a point echoed in investor outreach research.
Why Follow-Ups Matter in Investor Outreach
Investors receive hundreds, sometimes thousands, of pitches. Emails get buried, skimmed, or deferred – especially during busy seasons.
Silence after your first email is not a signal of rejection. It is usually just inbox noise.
Here is what the data shows about investor outreach response rates:
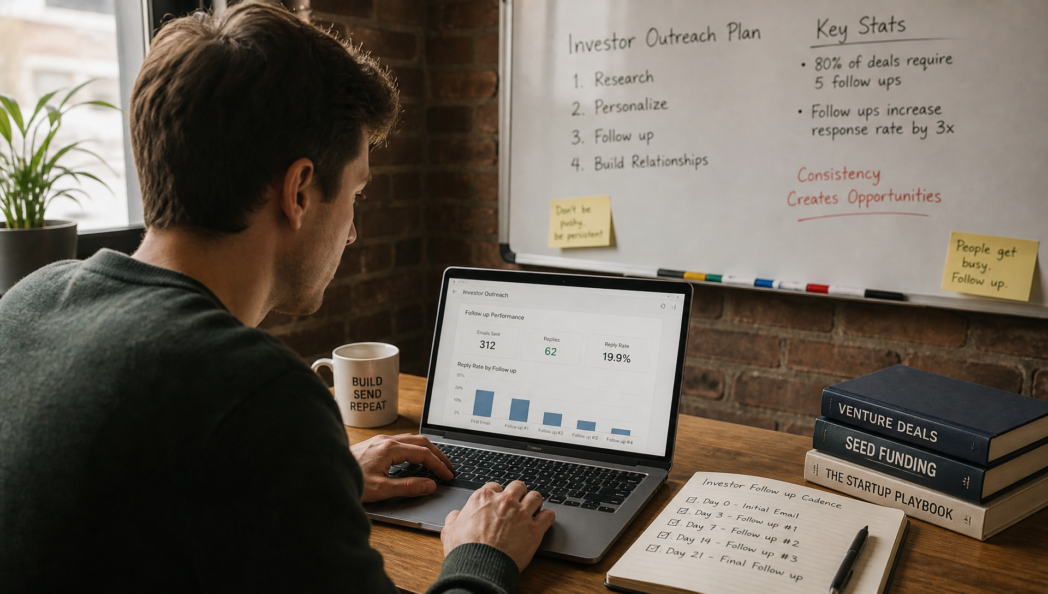
- 1st email: 18% response rate
- 2nd email: +11% additional responses
- 3rd email: +6% additional responses
- 4th email: +3% additional responses
Nearly 40% of positive responses come from follow-ups, not the initial email.
Broader cold email studies back this up. A dataset of 20 million+ emails found that campaigns with 2–3 follow-ups reached around 27% reply rates, compared to just 9% with no follow-ups – roughly a 3x lift. Sequences with 3–5 follow-up steps deliver about double the reply rate of sequences with zero follow-ups.
The practical takeaway for founders is straightforward. One email is almost never enough. A structured sequence of follow-up messages is both more professional and more effective than a single pitch sent into the void.
Follow-ups also signal something important to investors: you are organised, persistent, and serious. A founder who gives up after one ignored email does not exactly project confidence.
The key rule, as outlined in this startup guide to investor outreach, is that good follow-up emails must add value. They should not simply say “bumping this to the top of your inbox.” Each message needs a reason to exist.
Investor Follow Up Reply Rate Stats and What They Mean
Understanding investor follow up reply rate stats helps you set expectations and diagnose problems in your sequence.
The patterns that show up consistently across fundraising and cold outreach data are:
Highest reply rates come from the first few touches
- The initial email captures investors who are both interested and actively checking their inbox.
- The first follow-up picks up people who missed or skimmed the original message.
- The second follow-up still generates meaningful incremental replies, especially when it includes new traction or context.
Diminishing returns kick in after the third or fourth follow-up
The +11%, +6%, +3% decay curve across the 2nd, 3rd, and 4th emails is a clear pattern. After 4–5 total touches, the data shows limited benefit to additional outreach.
Key variables that influence your reply rate more than volume
- Investor list quality: Matching on fund thesis, stage, geography, and cheque size can easily double your effective reply rate. Warm intros often see 50%+ response rates. Cold email benchmarks target 5–10% positive replies.
- Email length: Fundraising outreach data shows 100–200 word emails reach around 25% response rates, compared to just 8% for emails over 300 words.
- Founder credibility and traction: Prior exits, brand-name customers, revenue milestones, and committed investors all lift reply rates.
- Market timing: Hot sectors or macro tailwinds improve investor appetite and responsiveness.
The conclusion here, according to this analysis of underperforming outreach, is that if your reply rate stats are low, the issue is usually not the number of follow-ups you are sending. It is more likely targeting quality, email length, or the strength of your proof points, a view shared across broader investor outreach research.
Best Number of Follow Ups for Investor Outreach
The best number of follow ups for investor outreach is not one. It is a structured sequence.
Here is a simple framework for choosing the right number:
| Follow-Up Count | When to Use It |
|---|---|
| 1–2 follow-ups | Warm intro, strong existing relationship, investor has already signalled a clear pass |
| 3 follow-ups | Standard investor outreach sequence for most founders |
| 4 follow-ups | High-fit investor, time-sensitive round, prior engagement or email open/click recorded |
| More than 4 | Only when you have a meaningful company update or new reason to reconnect |
The minimum for most cold outreach is 2 follow-ups. The standard is 3. The ceiling for most cases is 4.
Going beyond 4 follow-ups without new information crosses the line from persistence into pressure, according to investor follow-up cadence guidance. That damages your reputation and reduces the chance of re-engaging the investor in a future round.
Follow-Up Cadence – When to Send Each Email
Timing matters as much as the number of follow-ups you send.
Recommended spacing:
- Follow-up 1: 3–5 business days after the initial email
- Follow-up 2: 5–7 business days after follow-up 1
- Follow-up 3: 7–10 days after follow-up 2
- Final close-the-loop email: Approximately 1 week after follow-up 3, or after a meaningful company update
What to avoid:
- Daily follow-ups or multiple messages in the same week
- Following up without any new information to share
- Aggressive “just checking in” language with no substance
- Sending at odd hours or over weekends when your message is likely to get buried
As explained in investor outreach timing research, the spacing between touchpoints gives investors time to respond, check your deck, or loop in a partner. Sending too quickly signals anxiety. Spacing your messages correctly, per this fundraising communication guidance, signals discipline.
What Each Investor Follow-Up Should Say
Every follow-up in your sequence needs a purpose. Here is what each one should do, based on this investor outreach email template guide:
Follow-up 1 – Short reminder
- Keep it to 3–5 sentences
- Restate your sharpest traction point
- Restate your one clear ask (a 15–20 minute intro call works well)
- Frame it as making sure the email did not get lost – not chasing
Follow-up 2 – New context or proof point
- Add something concrete: a new customer win, a revenue milestone, a notable investor commitment, or a crisp market insight aligned with their thesis
- Stay under 150 words
- Include one clear call to action
Follow-up 3 – Urgency and relevance
- Mention round dynamics: how much is already committed, your target close date, or an upcoming milestone
- Reference why this specific investor is a strong fit: their portfolio, their stated thesis, a recent investment they made
- Keep it polite and specific – avoid artificial pressure
Final close-the-loop email – 2–3 sentences
- Acknowledge that you have not heard back and that you will pause direct outreach
- Leave the door open: something like “We will share key milestone updates from time to time – happy to reconnect when the timing is right”
- This protects the relationship while stopping the chase
Never send identical follow-ups repeatedly. Each message needs to move the conversation forward.
Effective Investor Follow-Up Angles That Drive Replies
If you are stuck on what to say in each follow-up, here are the angles that work best, drawn from this startup guide to pitching and follow-ups:
Traction update
- Revenue growth since your last email
- New user milestone or retention metric
- A notable customer win or partnership signed
Social proof
- A new angel investor or advisor who has joined
- Another fund expressing interest or soft-circling
- A brand-name customer or strategic partner
Timing signal
- “We are taking first meetings this week”
- “Our lead investor is finalising paperwork – this round closes in four weeks”
Investor fit reference
- Reference a specific portfolio company of theirs that shares your market
- Connect your thesis to a public statement or investment thesis they have published
Scarcity or urgency
- Round closing timeline
- Limited allocation remaining
- Upcoming partner meeting schedule that creates a natural deadline
Use a different angle in each follow-up. Repeating the same frame signals that you have nothing new to say, as outlined in this outreach email template resource.
When to Stop Following Up With Investors
Persistence is a virtue in fundraising. But there are clear stopping points.
Stop active follow-ups when:
- 3–4 thoughtful, substantive follow-ups have gone unanswered
- You confirm the investor is outside your stage, sector, geography, or cheque size
- The investor has explicitly passed on the round
- You have no new information to add and messages are becoming repetitive
Transition to a long-term update cadence instead:
Once you stop direct follow-ups, per this investor follow-up cadence guide, move the investor onto a monthly or quarterly update list. These updates should cover:
- Revenue and growth metrics
- Product milestones
- Key hires
- New customers or strategic partners
The call to action in these updates should be light: something like “Happy to share more detail if the timing looks better on your end.”
This approach, as noted in this outreach troubleshooting guide, protects goodwill and creates future touch points without feeling like pressure. There is an important distinction here between active fundraising follow-ups (short-term, goal-focused, higher frequency) and investor updates (long-term relationship building, lower frequency, broader content).
An investor who passes now may be the right partner for your next round.
Common Mistakes Founders Make With Investor Follow-Ups
These are the patterns that burn relationships and reduce reply rates, according to fundraising outreach best practices:
- Sending too few follow-ups. Most founders give up after one or two attempts, leaving nearly 40% of potential positive responses on the table.
- Sending too many generic follow-ups. Copy-pasting the same message repeatedly signals poor preparation and wastes the investor’s time.
- Following up too quickly. Daily or every-other-day emails are widely discouraged. Recommended spacing starts at 3–5 business days.
- Using guilt, pressure, or overly casual language. Phrases like “I really need an answer” or “Just wanted to bug you again” undermine your positioning.
- Not personalising the investor outreach. Generic templates with no reference to portfolio, thesis, or recent activity produce lower response rates.
- Not tracking reply rates by sequence step. Without data, you cannot tell which email in your sequence is working and which is not.
- Focusing on email volume instead of investor fit. Sending 500 poorly targeted emails will not outperform sending 100 well-targeted ones.
- Asking for money before asking for a meeting. Your first goal is a 15–20 minute introductory call, not a term sheet.
- Continuing to push after a clear pass. Respect the “no.” Move on and re-engage with progress later.
See this guide on fixing underperforming outreach and this startup pitching and follow-up guide for more detail.
How to Improve Investor Follow-Up Reply Rates
If your response rate is low, adding more follow-ups is rarely the fix. Here is where to focus instead, drawing on investor outreach resource hub research:
Better investor targeting
- Build your list based on fund thesis, stage, geography, cheque size, and portfolio signals
- A well-targeted list of 100 investors will outperform a generic list of 500
Stronger subject lines
- Personalised and specific performs much better than generic
- Example: “Following up – [Portfolio company]-adjacent SaaS, 120% net revenue retention”
Shorter emails
- 100–200 word emails generate around 25% response rates
- Emails over 300 words drop to around 8%
Clearer ask
- One simple call to action per email: a 15–20 minute call, permission to send a deck, or feedback on fit
- “Let me know what you think” is not a call to action
More personalised opening
- Reference their recent investment, published thesis, or public commentary on a related topic
Concrete traction signals
- Include revenue, growth rates, retention, logo wins, pipeline, or usage metrics
- Credibility signals (prior exits, notable advisors, committed investors) lift reply rates significantly
Warm introductions where possible
- Warm intros can yield 50%+ response rates vs 5–10% for cold emails
- Prioritise building mutual connections before reaching out directly
Tracking and refining
- Monitor open rates, reply rates, and response by sequence step
- Low open rate usually points to a subject line or deliverability issue
- Low reply rate usually points to a targeting or pitch quality issue
See this investor outreach email template guide for ready-to-use structures.
Warm Intro vs Cold Investor Follow-Up Strategy
The best number of follow ups for investor outreach is different depending on your outreach channel, as explained in this fundraising outreach troubleshooting resource.
Warm introductions
- More relationship-sensitive by nature
- Fewer follow-ups are needed because reply rates are significantly higher
- 1–2 follow-ups is usually sufficient before going back to your mutual contact
- Always reference the person who made the introduction in your message
- After one or two unanswered emails, update the introducer and ask whether it still makes sense to pursue
Cold investor outreach
- Requires stronger personalisation and more persistence
- Usually needs 3–4 touchpoints before you can reasonably conclude there is no interest
- Each follow-up must carry a new proof point or context to justify the send
- Personalising the first line to something specific about that investor is essential
If your warm intro pipeline is thin, cold outreach with a highly targeted list and strong personalisation is your best lever, per this investor outreach pitching guide. The follow-up sequence matters more in cold outreach because the relationship baseline is lower, a point also made in this fundraising communication tips resource.
Suggested Investor Follow-Up Sequence You Can Copy
Here is a practical sequence with guidance on each step, adapted from fundraising outreach best practices and this follow-up cadence guide:
Email 1 – Initial outreach (Day 0)
- Length: 50–150 words
- Content: Personalised opening, one-line company description, two or three traction proof points, one clear ask
- Subject line: Specific, personalised, under 8 words
Follow-up 1 – Gentle reminder (Day 3–5)
- Length: 3–5 sentences
- Content: Short restate of the ask, one fresh data point (metric, customer, or investor-fit reference)
- Subject line: Reply to the original thread
Follow-up 2 – New proof point (Day 7–10)
- Length: Under 150 words
- Content: New customer win, revenue milestone, notable investor commitment, or market insight relevant to their thesis
- Subject line: Reply to thread, or a new line if enough time has passed
Follow-up 3 – Urgency and fit (Day 14–21)
- Length: Under 150 words
- Content: Round progress (% committed, close timeline), direct reference to investor fit (portfolio, thesis), single clear meeting ask
- Subject line: Reply to thread
Final close-the-loop email (Day 30+)
- Length: 2–3 sentences
- Content: Acknowledge no response, pause direct outreach, leave the door open for future milestone updates
- Subject line: Reply to thread
Keep every email short, specific, and direct. One new value point per email. One call to action per email. No exceptions.
See also this investor outreach email template and this investor outreach resource for additional formatting ideas.
How to Measure Your Own Investor Follow Up Reply Rate Stats
Generic benchmarks give you a starting point, but your own data is what actually matters.
Track these metrics for every outreach campaign:
- Total investors contacted
- Open rate by email number
- Reply rate by email number
- Positive vs negative reply breakdown
- Meetings booked from each sequence step
- Conversion from first meeting to second call
How to interpret what you find:
- Low open rate usually means a subject line problem or deliverability issue. Shorten your subject lines and check your sending domain health.
- Low reply rate despite decent open rates usually means a targeting problem or a pitch quality problem. Review your investor list and tighten your email copy.
- Replies only arriving after the second or third follow-up is a signal that your cadence is working – keep the spacing consistent.
- No replies after 3–4 touches usually means poor investor fit, weak positioning, or both. Audit your list before sending more volume.
- High reply rate but low meeting booking rate suggests your email hooks attention but your ask or pitch is unclear. Sharpen the call to action.
Measuring reply rates at each step of your sequence, as recommended by cold email sequence research and this outreach troubleshooting resource, is the only way to know whether adding another follow-up is worth it or whether the real problem is earlier in your funnel.
Practical Recommendation by Fundraising Scenario
Here is a direct answer for each common situation, based on fundraising outreach best practices:
Pre-seed cold outreach
- Recommended: 3–4 follow-ups after the initial email
- Rationale: Cold campaigns need more touchpoints to overcome inbox noise and low baseline relationship
Seed round with warm intro
- Recommended: 2–3 follow-ups, then re-engage your mutual contact
- Rationale: Higher baseline reply rate means fewer touches are needed; relationship management matters more here
Series A and above – institutional outreach
- Recommended: 2–3 highly tailored follow-ups, no more
- Rationale: Senior partners at larger funds expect concise, high-quality outreach; over-following up damages your credibility
Previously interested investor (met before, timing was off)
- Recommended: Follow up until you get a clear answer, but only with relevant updates
- Rationale: Prior interest is a strong signal; re-engage with traction and milestone updates that change the picture
Investor who passed on the current round
- Recommended: No more follow-ups on this round; move to quarterly milestone updates
- Rationale: Most investors expect you to respect a clear “no”; the relationship is worth more than a second push on the same raise
Investor who requested your deck
- Recommended: 2–4 follow-ups starting with a confirmation of receipt
- Rationale: You have explicit permission; follow-ups should confirm receipt, answer likely questions, and propose a clear next step
More scenario-specific guidance can be found in this investor outreach resource, this outreach troubleshooting guide, and this startup guide to pitching and follow-ups.
Conclusion
For founders asking how many follow up emails to send investors, the data-backed answer is clear: send the initial email plus 2–4 thoughtful follow-ups, with around 3 meaningful touchpoints before you close the loop and move on.
But the number alone is not what drives results. Quality, timing, personalisation, and investor fit matter far more than simply sending more emails. Nearly 40% of positive responses come from follow-ups rather than the initial pitch – but only when each follow-up adds something real.
The practical playbook looks like this:
- Build a targeted investor list matched to your stage, sector, and round size
- Send a concise, personalised initial email with clear traction signals and one ask
- Follow up 2–4 times with increasing context: a reminder, a proof point, urgency, and a close-the-loop message
- Track your investor follow up reply rate stats at each step and refine accordingly
- Stop direct follow-ups after 3–4 unanswered touches and shift to a long-term update cadence
The founders who raise efficiently are not the ones who send the most emails. They are the ones who send the right emails to the right people at the right time – and stop when further outreach no longer adds value.
For further reading, see fundraising outreach best practices, this follow-up cadence guide, this outreach troubleshooting resource, and this investor outreach resource hub.
Frequently Asked Questions
How many follow up emails should I send an investor before giving up?
Most founders should send 2–4 follow-ups after the initial email, with 3 being the standard sequence. Stop after 3–4 unanswered, substantive follow-ups and shift the investor to a lower-frequency update list rather than continuing to chase.
Is it unprofessional to follow up multiple times with an investor?
No – a structured, spaced-out follow-up sequence is considered professional, not pushy. What damages credibility is sending repetitive, low-value messages too frequently or without any new information.
How long should I wait between investor follow-up emails?
Space your first follow-up 3–5 business days after the initial email, the second 5–7 business days later, and the third 7–10 days after that. A final close-the-loop message can go out roughly a week after the third follow-up.
Do warm introductions need fewer follow-ups than cold outreach?
Yes. Warm introductions typically need only 1–2 follow-ups before you re-engage your mutual contact, since reply rates are significantly higher. Cold outreach usually requires 3–4 touchpoints because the relationship baseline is lower.
What should I do if an investor never responds after several follow-ups?
After 3–4 thoughtful follow-ups with no response, stop active outreach and move the investor onto a monthly or quarterly update list covering revenue, product milestones, and key hires. This preserves the relationship for a future round without feeling like pressure.
Does adding more follow-up emails always improve reply rates?
No. Reply rates show diminishing returns after the third or fourth follow-up. If your reply rate is low, the issue is usually investor targeting, email length, or personalisation rather than the number of emails sent.